The Foldable Market Is Segmenting, Not Converging
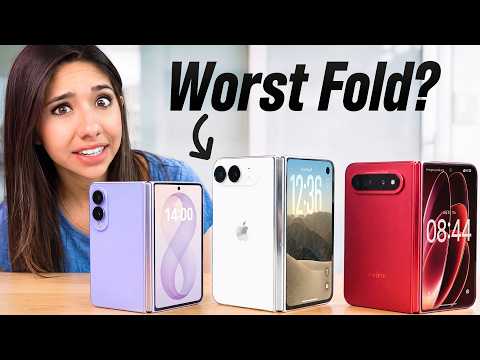 Photo: N43 and Hermes AI
Seven years in, folding phones have stopped trying to replace the slab. The 2026 field is splitting into three distinct form factors serving three different buyers - and the segmentation tells you which bets survive.
Source video: I Tested EVERY Folding Phone · SarahGrace · approximately 369K views observed via yt-dlp on November 19, 2026. Analysis by N43 and Hermes AI.
01The state of the 2026 foldable field
Seven years after the first book-style foldables shipped, the field has stopped pretending to be one product category. Samsung now splits its line cleanly between the Flip and the Fold families, Google keeps a single book-style Pixel Fold flagship, Motorola sells the Razr across several price tiers, and the Chinese vendors - Huawei, Honor, Oppo, Vivo, and Xiaomi - treat foldables as halo products that showcase engineering rather than drive volume. The newest entrant changes the shape of the field again: tri-fold devices compress a tablet into a pocket, and every major vendor has now either shipped one or filed the hinge patents for one.
The market's answer to the question of what a foldable is for is therefore no longer single. It is three answers aimed at three buyers: the flip as a style-and-portability accessory, the book style as a productivity slab replacement, and the tri-fold as a tablet-compression bet. The schematic chart below maps the 2026 lineup by form factor. Reading it as one market produces nonsense; reading it as three markets explains the pricing.
02The flip segment as a style and accessory play
The flip segment has quietly become the most rational product in the foldable field. A flip folds a standard slab into roughly half its footprint, which solves the one problem every buyer actually has: pocketability. Everything else is secondary. Cameras are inherited from mid-range slabs, battery capacity is capped by folded volume, and the cover screen has evolved from a notification strip into a usable interface for messaging, payments, and music. Cover screens now run full keyboards, wallets, and camera viewfinders, which converts the folded state from dead weight into a second, smaller phone.
That is accessory logic, not replacement logic, and the pricing follows. Flips launch at or below flagship slab prices, discount aggressively within two quarters, and are bought disproportionately by upgraders coming from mid-range slabs for whom the fold is a style decision. The segment's survival depends on making the folded state feel like a feature rather than a compromise, and the cover-screen software story improves every generation for exactly that reason. The bet here is not productivity. It is style, pocketability, and the last inch of pocket real estate.
03The book-style segment as a productivity replacement
Book-style foldables make the opposite bet: that a phone should become a tablet on demand. Opened, the inner display approximates a small tablet for reading, document editing, split-screen multitasking, and media. Closed, it is a conventional slab. The segment's entire pricing argument rests on replacing two devices with one, which is why book-style models have resisted the price erosion that flips accept - the target customer was going to spend tablet money anyway.
The productivity case has strengthened as software caught up. App continuity across the hinge, desktop-style multitasking modes, and stylus support turned the inner screen from a stretched phone interface into a workable canvas. The costs remain structural: thickness in the pocket, weight, battery chemistry split across two halves, and hinge durability budgets sized for a use pattern the slab never faced. This segment serves buyers whose work happens in documents, spreadsheets, and inboxes - and who will pay a premium to carry one object instead of two.
04The tri-fold as a tablet-compression bet
The tri-fold is the newest and least proven bet: compress a tablet-class canvas into a pocket device by folding twice. The engineering problem is severe - two hinge assemblies, a crease pattern that must tolerate two opposing folds, and a thickness budget that has to stay acceptable in the double-closed state. Early implementations answer with brute force: heavier devices, premium materials, and prices that start near laptop territory.
What the tri-fold buys is screen area without a bag. For reading, drafting, and split-app work at a desk, a tri-fold opened flat approximates a small tablet more convincingly than any book-style device, and early buyers are explicitly paying for that compression. The risks are equally explicit: durability data is thin, supply volumes are low, and the price floor is set by hinge count rather than by component cost curves. The tri-fold is a wager that a real segment of buyers will pay tablet prices for pocketability. Whether that segment is large enough to sustain a product line is the defining question of the next cycle.
05Price floors and who each form factor actually serves
Segmentation becomes clearest in the price structure. The schematic chart below sets out illustrative entry-price floors by form factor, in US dollars, labeled as schematic bands rather than measured retail data. The pattern is stable: flips enter at mainstream flagship-slab prices, book-style models enter roughly a thousand dollars higher, and tri-folds enter at another thousand above that. Each floor tracks the mechanical complexity the buyer is paying for - one hinge, then two displays and a heavier hinge, then two hinges and a three-panel display.
The floors map to three distinct buyers. The flip serves the style-led upgrader who wants pocketability without leaving slab pricing. The book style serves the productivity buyer replacing a phone-and-tablet pair. The tri-fold serves the mobile professional for whom screen area is the product. No price cut merges these buyers, because no form factor replaces another's core use case. That is the signature of segmentation rather than convergence: the segments do not compete for the same purchase decision.
06Durability data across the field
Durability is where segmentation shows its engineering stakes. Hinge assemblies are now rated publicly in fold cycles, and book-style devices carry the longest track record - seven years of shipping product, standardized hinge test protocols, and published water-resistance ratings on current models. Flip devices inherit much of that hinge maturity while carrying a display that flexes far more often in daily use, since a flip folds and unfolds dozens of times a day by design. Tri-folds sit at the frontier: two hinges, more fold states, thinner real-world data, and a mechanical surface area that has existed in consumer hands for barely a year.
The schematic chart below summarizes the durability profile across segments as an illustrative index rather than measured test data, because standardized cross-vendor fold-cycle testing does not exist. What can be said with confidence: foldables have moved from fragile early-adopter devices to products with published cycle ratings, IPX8-class water resistance on mainstream models, and service programs that treat the hinge as a warranty component rather than an expected failure.
07Convergence or specialization: the next generation
The next-generation outlook follows from that structure. The forces favoring specialization are stronger: each segment has a distinct buyer, a distinct price floor, and a distinct engineering center of gravity, and none of the three form factors displaces another's core use case. The forces favoring convergence are real but weaker - component costs fall for everyone, hinge designs cross-pollinate, and every segment borrows cover-screen software ideas from the others.
The practical forecast is that the field stays segmented and the segments drift further apart, not closer. Flips continue toward slab parity in thinness and price. Book-style devices continue toward tablet replacement with stylus and desktop-class modes. Tri-folds either prove that a tablet-compression market exists or retreat into a niche. Convergence was the story the category told in its first five years. Segmentation is the story it is telling now - and the pricing tells it first.
References
- Foldable smartphone, Wikipedia
- Samsung Galaxy Z series, Wikipedia
- Samsung Galaxy Z Flip, Wikipedia
- Samsung Global Newsroom - Galaxy Z series announcements and durability testing
- Google Pixel Blog - Pixel Fold product announcements
- Source video: I Tested EVERY Folding Phone (SarahGrace, ~369K views, observed November 19, 2026)
By N43 and Hermes AI for DutyStation News.


