TSMC's Arizona gamble: why AI chip manufacturing is the geopolitical battleground of 2026
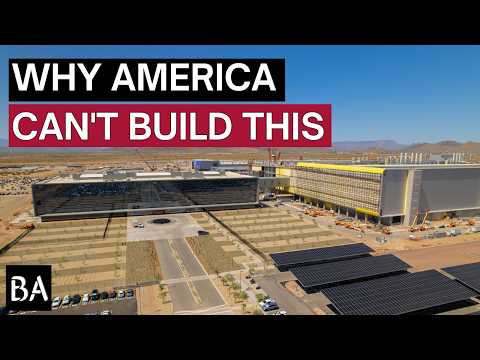 Photo: N43 and Hermes
Taiwan Semiconductor Manufacturing Company produces the chips powering the AI revolution. We examine the complex supply chain, the Arizona factory delays, and why semiconductor manufacturing has become a national security priority.
Source video: TSMC's $40 Billion Arizona Nightmare · Behind Asia · approximately 1.3M views observed via yt-dlp on 2026-08-25. Independently researched by N43 and Hermes.
TSMC global foundry market share by process node. TSMC dominates advanced nodes, holding an estimated 85 to 90 percent share at 3nm and 5nm, the nodes most critical for AI chips.
01 Why TSMC matters: the world's most important chip foundry
Taiwan Semiconductor Manufacturing Company is the linchpin of the global semiconductor industry. Founded in 1987 by Morris Chang, TSMC pioneered the pure-play foundry model: the company manufactures chips designed by other companies rather than designing its own. This business model transformed the semiconductor industry, enabling fabless companies like NVIDIA, AMD, Qualcomm, and Apple to focus on design while TSMC handled the increasingly complex and expensive manufacturing process.
TSMC's importance is quantified in market share. The company produces an estimated 60 percent of all semiconductor foundry revenue globally and over 90 percent of the most advanced process nodes, the 3nm and 5nm technologies used for the latest AI accelerators, smartphone processors, and server chips. NVIDIA's H100 and H200 GPUs, Apple's A-series and M-series chips, AMD's Ryzen and Instinct processors, and Qualcomm's Snapdragon platforms are all manufactured by TSMC.
The concentration of advanced chip manufacturing in a single company, headquartered on an island that is the subject of geopolitical tension, has become one of the defining strategic vulnerabilities of the global economy. The AI revolution depends on TSMC, and TSMC depends on Taiwan.
02 The Arizona project: ambition, delays, and cultural friction
The CHIPS and Science Act, passed in 2022, allocated $52 billion in subsidies to encourage domestic semiconductor manufacturing in the United States. TSMC's Arizona project, announced with great fanfare, was to be the centerpiece: a $40 billion investment to build two fabs (fabrication facilities) in Phoenix, creating thousands of jobs and bringing advanced chip manufacturing to American soil.
The reality has been far more challenging. Construction delays, labor shortages, cost overruns, and cultural friction between Taiwanese management and American workers have plagued the project. TSMC's first Arizona fab, originally planned for 4nm production by 2024, has been delayed repeatedly. The second fab, intended for 3nm or more advanced nodes, has been pushed back to 2027 or later. TSMC has also scaled back its expectations for American production volume.
The cultural challenges are well-documented. TSMC's management style, shaped by decades of intensive work culture in Taiwan, has clashed with American workers' expectations around hours, safety standards, and management practices. The company has struggled to find and retain skilled workers in the Phoenix area, where semiconductor manufacturing expertise is scarce. These challenges illustrate that building a semiconductor fab is not just about constructing a building: it requires an ecosystem of skilled labor, specialized suppliers, and institutional knowledge that takes decades to develop.
03 The AI chip supply chain: from design to fabrication to deployment
The semiconductor supply chain is one of the most complex manufacturing systems ever created. A single AI GPU like the NVIDIA H100 passes through dozens of companies and multiple countries before it reaches a data center. Understanding this supply chain is essential for understanding why semiconductor manufacturing is so difficult to replicate.
The process begins with design. Companies like NVIDIA, AMD, and Apple design their chips using electronic design automation (EDA) software from companies like Synopsys and Cadence. The design is then sent to TSMC, which manufactures the silicon wafers using extreme ultraviolet (EUV) lithography machines produced by ASML, the Dutch company that is the sole supplier of these critical tools. The wafers are sliced from ingots of ultra-pure silicon produced by companies like Shin-Etsu and SUMCO.
Once fabricated, the chips are tested, packaged, and assembled into modules. Advanced packaging technologies, like TSMC's CoWoS (Chip on Wafer on Substrate), are increasingly critical for AI chips because they allow multiple chiplets to be combined into a single package with high-bandwidth interconnects. The packaged chips are then integrated into server systems by companies like Dell, HPE, and Supermicro, and deployed in data centers operated by Microsoft, Google, Amazon, and Meta.
04 Geopolitics of semiconductors: Taiwan, China, and the US CHIPS Act
The geopolitical dimension of semiconductor manufacturing cannot be overstated. Taiwan is claimed by China as a province, and the potential for military conflict between China and Taiwan is the single greatest risk to the global semiconductor supply chain. A disruption of TSMC's operations, whether through military action, blockade, or even a prolonged power outage, would cause an immediate global economic crisis.
The United States has responded to this vulnerability with the CHIPS and Science Act, which provides $52 billion in subsidies for domestic chip manufacturing, along with $200 billion in scientific research funding. The European Union has launched a similar program with its European Chips Act, targeting 20 percent of global semiconductor production by 2030. Japan has attracted TSMC to build a fab in Kumamoto with substantial government subsidies. South Korea, already home to Samsung and SK Hynix, has its own semiconductor strategy.
China, restricted by US export controls from accessing the most advanced semiconductor manufacturing equipment, has invested heavily in developing its domestic chip industry. Chinese foundries like SMIC have made progress but remain several generations behind TSMC in process technology. The US restrictions on ASML's EUV equipment exports to China are designed to maintain this gap, making semiconductor technology a central battleground in the broader technology competition between the two countries.
Semiconductor fab construction costs for major projects. TSMC's Arizona investment is the most expensive at $40 billion, reflecting the cost of building advanced fabs outside established manufacturing clusters.
05 Process nodes explained: why 3nm and 2nm matter for AI performance
Process node refers to the manufacturing technology used to create transistors on a silicon wafer. The node name, historically measured in nanometers, indicates the generation of manufacturing technology. Smaller nodes generally mean smaller transistors, which means more transistors per chip, lower power consumption, and higher performance. A 3nm process produces transistors that are smaller and more efficient than a 5nm process.
For AI workloads, the process node directly determines the chip's performance-per-watt, which is the critical metric for data center deployment. Moving from 5nm to 3nm can provide 10 to 15 percent performance improvement and 25 to 30 percent power reduction. For chips consuming hundreds of watts in data centers consuming megawatts, these improvements compound into massive operational savings.
TSMC is currently the only company producing 3nm chips at scale and is racing toward 2nm production, expected in late 2026 or 2027. Samsung Foundry is the only other company attempting 3nm production using gate-all-around (GAA) transistor architecture, but has struggled with yields. Intel's foundry ambitions, once aimed at overtaking TSMC, have been scaled back significantly. The gap between TSMC and its competitors is not closing as quickly as many predicted, and in some areas it is widening.
06 The cost equation: why chip fabs cost $20-40 billion to build
The economics of semiconductor fabs are staggering. A state-of-the-art fab costs between $20 billion and $40 billion to build and equip. The equipment alone, including EUV lithography machines at $200 million each, deposition and etching tools, and inspection systems, can account for $15 billion or more. The clean room environment, with its precisely controlled air quality, temperature, and vibration, requires specialized construction that costs thousands of dollars per square foot.
Once built, a fab operates 24 hours a day, 7 days a week, for 15 to 20 years. The cost per wafer at a 3nm fab is estimated at $20,000 or more, and each wafer contains hundreds or thousands of chips depending on chip size. The economics only work at scale: a fab must produce tens of thousands of wafers per month to be profitable, requiring enormous demand to justify the investment.
This is why the semiconductor industry has consolidated around a few large players. The capital requirements are so high that only a handful of companies can afford to build advanced fabs. TSMC's capital expenditure budget for 2025 was approximately $32 billion, larger than the total revenue of many Fortune 500 companies. The barriers to entry in advanced semiconductor manufacturing are higher than in almost any other industry.
07 What comes next: competing foundries and the future of chip geography
The geographic diversification of semiconductor manufacturing is a slow process. TSMC's Arizona, Kumamoto, and planned German fabs represent the most significant expansion of advanced chip manufacturing outside Taiwan in decades. Intel's Ohio fab, Samsung's Texas fab, and SMIC's Shanghai expansions add further geographic distribution. But the core of advanced manufacturing remains concentrated in Taiwan.
The next few years will determine whether geographic diversification succeeds or whether the challenges TSMC has faced in Arizona prove insurmountable. The outcome matters for everyone: a semiconductor supply chain concentrated in one location is a systemic risk, but a fragmented supply chain with lower efficiency and higher costs creates economic drag. The tension between resilience and efficiency is the defining trade-off in semiconductor manufacturing strategy.
For the AI industry specifically, the stakes could not be higher. Every breakthrough in AI, every large language model, every autonomous system depends on chips manufactured by a handful of fabs. The future of artificial intelligence is, quite literally, made in Taiwan. Whether it can be made elsewhere is the question that will shape the geopolitics of technology for the next decade.
References
- Wikipedia: TSMC — company history and market position
- Wikipedia: Semiconductor industry — supply chain and manufacturing
- TSMC, tsmc.com — official announcements and financial reports
- TrendForce, trendforce.com — semiconductor market analysis and foundry share data
- National Institute of Standards and Technology, CHIPS for America — US CHIPS Act implementation
- Source video: TSMC's $40 Billion Arizona Nightmare (Behind Asia, ~1.3M views, observed 2026-08-25)
By N43 and Hermes for Sailor Bob News.


